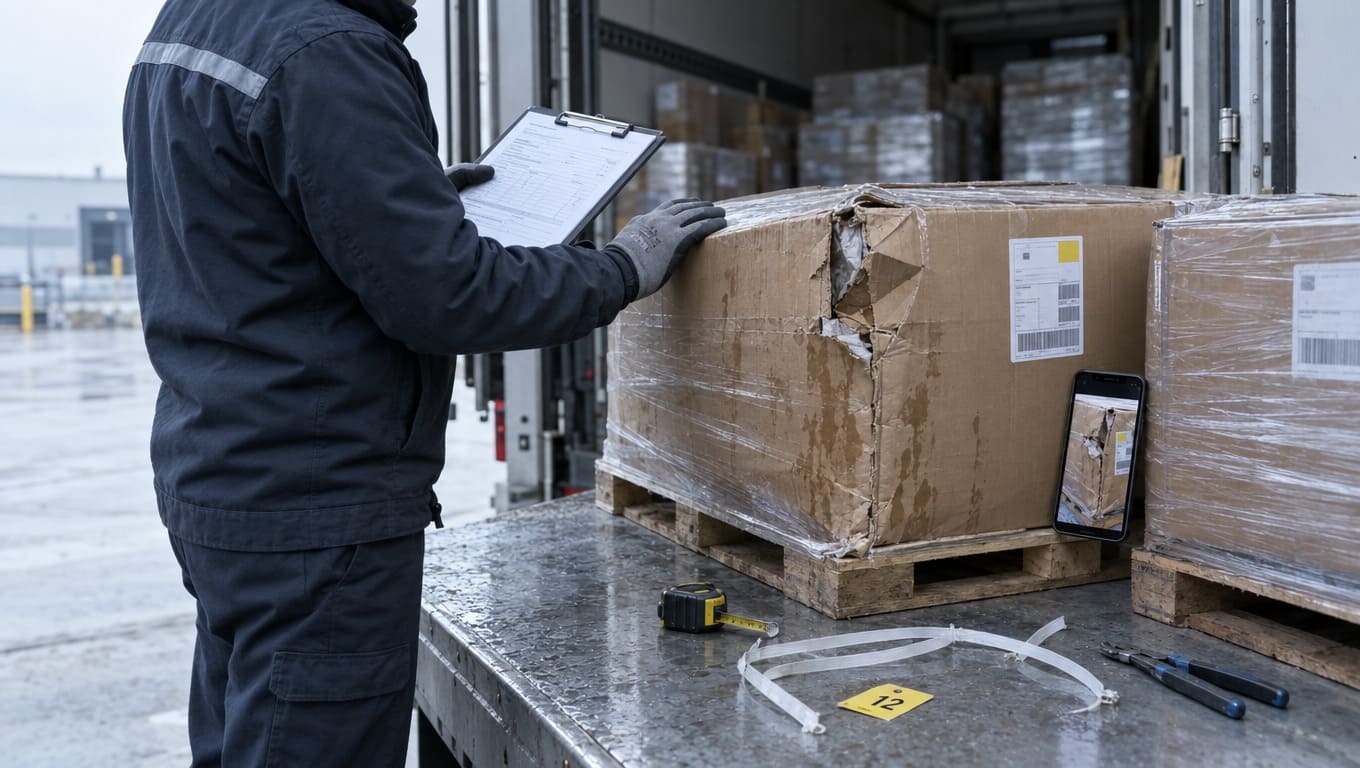
A surveyor inspection in logistics and cargo insurance is an independent assessment of the condition of the cargo, packaging, infrastructure, and transportation processes. The goal is not to “issue a beautiful report,” but to provide the insurer with facts for calculating the insurance premium and a policy to protect the interests of all parties to the contract.
International shipments are particularly sensitive to survey because there are more variables:
- several modes of transport (sea, air, road, rail transport);
- multi-stage logistics with reloading, storage at terminals, transshipment;
- different jurisdictions and documentation rules;
- change of carrier, terminal operators, loading and unloading conditions.
Without objective information, it is difficult for an insurance company to determine the real risks of damage, spoilage, or loss of cargo. In such cases, the insurer includes an increasing coefficient in the premium calculation simply due to uncertainty: “better safe than sorry.”
An independent surveyor reduces this information gap between the insurer, the cargo owner, and the carrier. He describes the actual conditions of packaging, loading/unloading, storage, and delivery, and records weaknesses and existing protective measures. Therefore, for international shipments, it is not just the existence of a report that matters, but its depth and quality: it is these factors that determine how noticeable the impact of the surveyor inspection will be on the cost of the insurance premium, the amount of possible payouts, and the future policy of insurance companies regarding this client.
How the Insurer Calculates the Premium and Where the Survey “Sits” in This Formula
The calculation of the cargo insurance premium relies not only on the type of cargo and the length of the route. Within insurance companies, there are fairly formalized risk assessment models into which surveyor data is gradually integrated.
In simple terms, the logic is as follows:
- A base rate is determined by the type of cargo and the geography of the route: bulk metal in containers and expensive equipment with oversized sections initially have different risks of damage and loss.
- Adjustments are made for transportation and handling conditions: quality of packaging and use of special solutions (rigid containers, vacuum, temperature control); the nature of warehousing and storage at terminals (open areas, indoor warehouses, security, climate); the number of reloads, connections, and changes in the mode of transport; the type of carrier: own fleet/vehicle park, hired or “gray” carriers.
- Loss history is taken into account: the frequency and severity of previous damage and spoilage of cargo on similar routes, for the same counterparties and logistics schemes.
The survey is “embedded” here in three formats:
- Risk survey prior to concluding the contract. It provides an initial risk assessment for a new transport scheme, supplier, route, or port. This is where more favorable terms can be set if the infrastructure and processes are confirmed.
- Loss prevention during the logistics process. The insurer receives evidence that recommendations are being followed and risks are actually reduced: this is the basis for reviewing the premium downwards.
- Loss adjustment in case of damage. The amount of compensation and subsequent increase or, conversely, stabilization of the premium depends on it: if the losses are accidental and the processes are generally stable, the surcharges are minimal.
A high-quality surveyor report reduces the “uncertainty” surcharge and allows for a move from an average “market” rate to an individual one. For example, for the same highly sensitive cargo in multimodal transport: without a survey, the insurer sees only general risks and applies an increasing coefficient; with a survey confirming the correct securing scheme and controlled conditions at each stage, the coefficient can be reduced by 10–30 relative to the standard surcharge.
Which Surveyor Findings Are Particularly “Sensitive” for the Insurer
A surveyor company report can take up dozens of pages, but the following sections influence the insurer’s decision on the premium most significantly:
- Description of the cargo and its vulnerabilities.
It is important how sensitive the cargo is to moisture, shock loads, temperature changes, vibrations, and theft. The insurer looks at whether the actual packaging and marking correspond to these features and whether special transportation conditions are provided (reefer containers, thermal loggers, cushioning materials).
- Infrastructure and logistics scheme.
The types of terminals, the area of responsibility of the parties during loading and unloading, the presence of indoor areas, lighting, security, video surveillance, as well as the number of transshipments and points where transport changes are noted. The more connections without standardized procedures, the higher the final risk of loss.
- Processes and control.
The key question for the insurer is: who manages the risks and how. The surveyor describes: who actually makes decisions and bears responsibility for loading and unloading; whether there are checklists, photo documentation, and staff briefings; how documents are processed when cargo is transferred between participants in the transport process.
- Previous experience and incidents.
Not only the facts of losses themselves are important, but also the actions taken after them: was an analysis of the causes conducted, were changes implemented, were new measures verified by a repeat survey. The recurrence of the same violations is a signal to increase the premium.
A report that records systemic problems (worn-out containers, overloaded warehouses, lack of regulations for cargo handling, ignoring past recommendations) almost inevitably leads to an increase in the premium or a tightening of insurance conditions. Conversely, the presence of standard operating procedures (SOP), constant auditing of suppliers and ports, and documented control at the transport and warehouse stages provide the insurer with arguments for a softer risk assessment and, accordingly, for savings on the insurance premium.
A useful question for self-checking: which elements of your loading, transportation, and storage processes would you prefer not to show the insurer? Usually, that is where the main risks are hidden, which an independent surveyor will see first.
When a Survey Saves on the Premium and When It Adds to the Cost
A surveyor inspection does not mean an automatic discount. It “aligns” the price, making it adequate to the real level of risks. In international logistics, this is particularly evident.
Survey as a basis for premium reduction:
- New route or new port infrastructure.
Without an inspection of the terminal and warehouse, the insurer applies an increasing coefficient for the unknown. After a survey confirming security, indoor areas, cargo handling regulations, and photo documentation during reloads, the coefficient can be reduced to the standard level or even lower – with high-quality infrastructure.
- Fragile or expensive cargo.
The client implements special packaging, damping pads, and controlled loading with the participation of the manufacturer’s engineer. The surveyor records the technology over several trips and notes the absence of damage. As a result, the insurer reduces the surcharge for fragility or leaves it only on high-risk sections (for example, during road transport on difficult route segments).
- Audit of suppliers and carriers.
An independent assessment of subcontractors’ work in loading/unloading, marking, storage, and documentation allows for the exclusion of part of the risks typical for the market from the coverage, thereby reducing the policy cost while maintaining the client’s level of protection.
When a survey leads to a price increase:
- Chaotic warehousing and overloaded areas. Cargoes are packed tightly together, marking is absent, there is no separation by risk type, and loading is conducted without instructions. The result is an increasing coefficient until the violations are eliminated and possible limitations on the compensation amount.
- Unmaintained or “gray” transport. Containers with corrosion, non-hermetic awnings, and the use of uncertified carriers are identified. The insurer refuses to apply the standard rate and increases the premium until the client reviews the logistics chain.
A survey does not “spoil the picture”; it shows it as it is. If, before the inspection, the client paid less than what the actual risks dictated, the difference would sooner or later return through losses and disputes over payouts. Correcting violations, conducting a repeat survey, and demonstrating progress is the classic path to a subsequent review of premiums in the client’s favor.
How to Organize Work with a Surveyor to Ensure the Premium is Economical and Justified
For clients, cargo insurance is often perceived as a “mandatory expense,” and the survey as a formality required by the insurer. In practice, with the right process organization, it is a tool for managing logistics costs and minimizing losses.
When to involve a surveyor:
- before concluding an insurance contract for new routes, cargo types, or when changing the base carrier;
- when moving to multimodal schemes where new terminals, forwarders, and transport modes are added;
- after a major loss or a series of small damages to determine root causes and adjust processes;
- when launching a new packaging or cargo handling scheme – to confirm the effectiveness of measures before negotiating the premium.
How to choose a surveyor company:
- experience in international transport and specific cargo categories (equipment, FMCG, pharma, liquid, bulk, etc.);
- recognition of reports by major insurance companies and brokers in the market;
- ability to combine cargo inspections with audits of suppliers, terminals, and logistics chains;
- a transparent approach to processing personal and commercially sensitive client data.
What to prepare for the inspection:
- descriptions of routes and transport scenarios, including connections and parties’ areas of responsibility;
- regulations for packaging, loading/unloading, storage, and interaction with carriers;
- loss statistics for several years and measures taken to reduce risks;
- samples of key documents (instructions, checklists, acceptance certificates, photo reports).
How to use survey results in negotiations with the insurer:
- emphasize eliminated non-conformities and new protective measures (for example, the implementation of a photo documentation system at each stage of cargo handling);
- provide results of supplier and terminal audits as evidence of the manageability of the entire transport chain;
- refer to the independent status of the surveyor and the risk assessment methodology accepted in the industry.
International inspection companies, such as GC LVS Global, usually work according to a comprehensive model: preliminary risk assessment, support during key stages of transportation, recommendations for process changes, and subsequent verification of implementation. This allows clients not just to get “another expense item,” but to build a systemic solution: reduce actual risks, achieve a justified premium, and reduce the number of disputed issues regarding compensation and payout amounts in case of insurance events.
When an Additional Survey is Justified and When It is an Unnecessary Expense
Not every international shipment needs to be accompanied by a separate surveyor. There are situations where the impact of a surveyor inspection on the cost of the insurance premium is particularly noticeable:
- complex multimodal schemes with a large number of connections and reloads;
- expensive, vulnerable, or reputationally critical cargoes (pharmaceuticals, electronics, unique equipment);
- routes, ports, terminals, or logistics service providers new to the insurer;
- the presence of a fresh loss history and the need to show the insurer that the causes have been eliminated.
An additional survey usually has little impact on the premium when dealing with bulk stable cargoes on long-established routes with minimal loss rates and good carrier reviews. In such cases, periodic inspections and standard control procedures are sufficient.
The practical criterion is simple: if the expected premium savings over the contract period or the reduction in the risk of major losses exceeds the cost of surveyor services, the inspection is economically justified. If the risks are small and well-studied, it makes sense to keep the survey as a scheduled quality control tool for the supply chain, rather than a mandatory condition for every cargo insurance application.