Every business owner needs clear answers to these questions, as inventory helps identify weaknesses in retail operations in a timely manner. Inventory is conducted based on an official order, and upon completion, the commission prepares a report.
What is Inventory in a Store
It is the process of verifying assets and their condition by comparing physical counts with accounting records. Inventory can be scheduled or unscheduled, complete or partial, and selective.
Inventory in a store is necessary to:
- Determine the actual quantity of goods in stock;
- Identify unrecorded items;
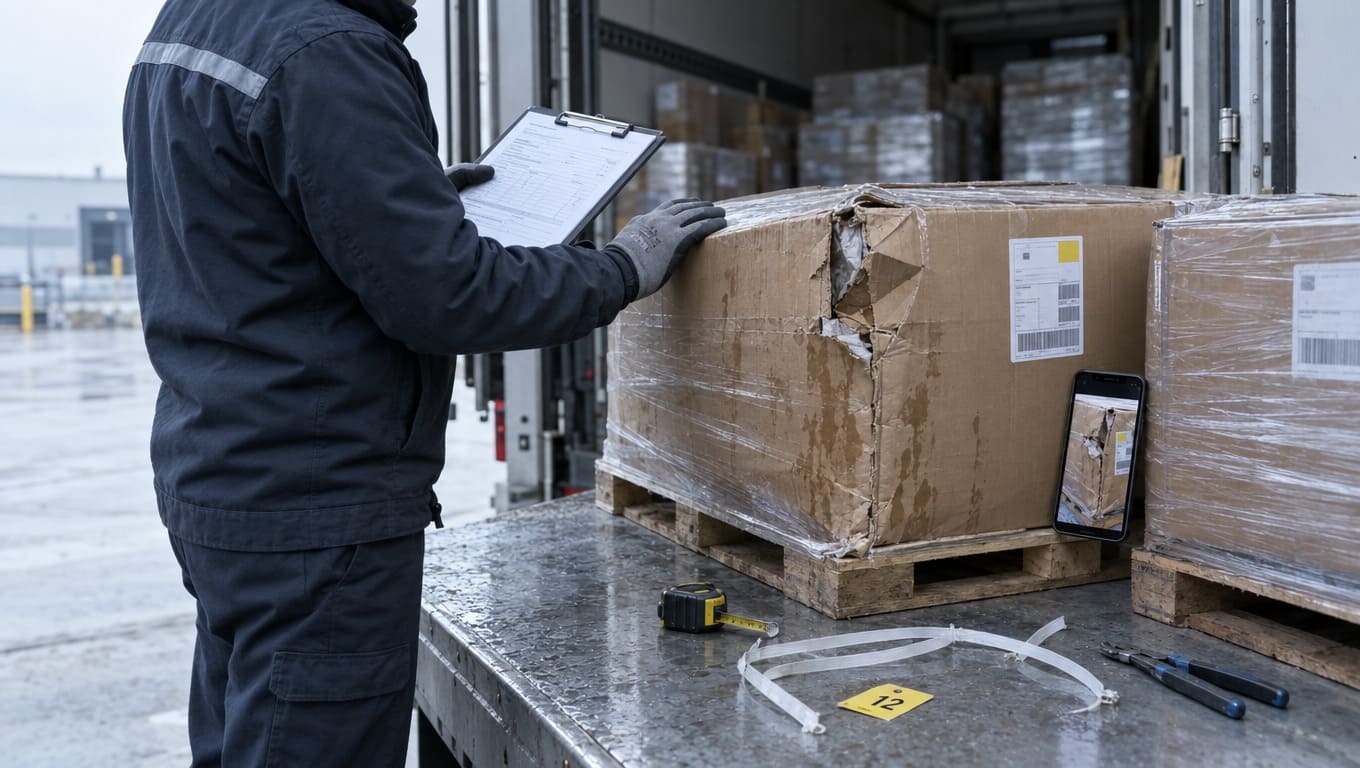
- Detect damaged goods or packaging;
- Identify misgraded items and surpluses;
- Monitor compliance with accounting and storage rules.
During inventory, expired or spoiled products may be discovered, which must be written off. Inventory also helps identify best-selling items and plan future purchases. Inventory in a store also aims to detect theft by employees or customers. Based on the results, decisions may be made to dismiss employees or recover damages.
Inventory is conducted according to the organization’s schedule, but it is mandatory before preparing annual financial statements and in other cases required by law. It is also mandatory when transferring goods (e.g., when selling the business) to a new owner or when changing the person responsible for asset custody. Unscheduled inventory is conducted after natural disasters, confirmed theft, or suspicion thereof.
Inventory Procedure
The most accurate inventory count is achieved when the cash register is closed and all goods have been received. For a full inventory, the store is usually closed, while for a partial inventory, only a specific department may be shut down.
The standard inventory process consists of several stages:
- Document preparation. The store manager issues an inventory order (Form INV-22), specifying the type and reason for inventory, the commission members, and the timeline. Additionally, blank forms for inventory lists and reports must be prepared. Both government-approved templates and custom forms may be used.
- Counting the goods. This can be done manually or by scanning barcodes, with the latter being faster and more convenient. Depending on the product, some items may need to be weighed. For partial inventory, a list of items to be checked is prepared first, and only those items are counted. For efficiency, products are counted by category—for example, vegetables and fruits first, followed by dairy and canned goods.
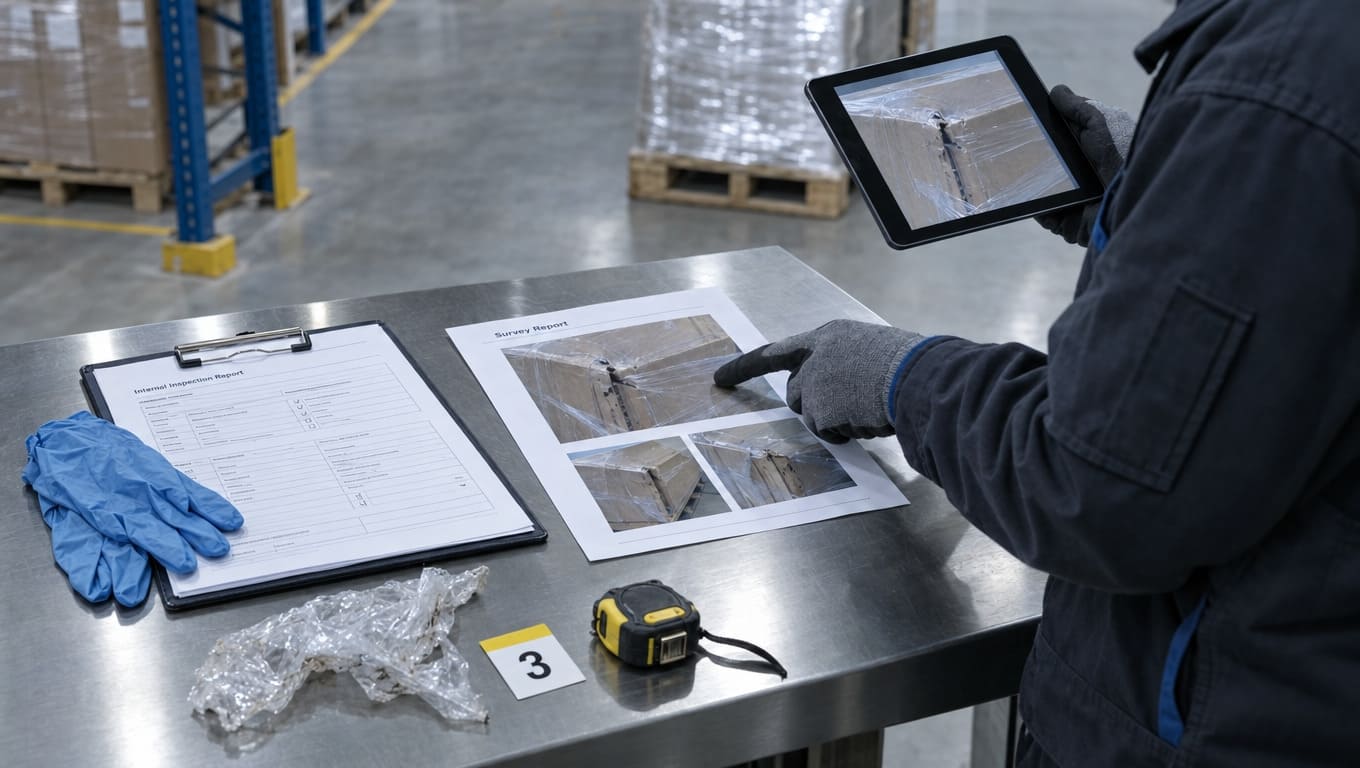
- Result analysis. All discrepancies (shortages, overages, misgrades) are recorded in the inventory report.
Inventory results are divided into preliminary and final. First, discrepancies must be double-checked—some items may have been misplaced or moved to another shelf. Based on the findings, a reconciliation report is prepared, after which the accountant finalizes the documentation. The final step is issuing an order approving the inventory results.
For goods subject to natural loss (e.g., evaporation, spillage), standard loss rates apply and must be reflected in the report. Spoiled or expired products must be written off after verification.
Store employees may serve on the inventory commission, but those responsible for asset custody cannot. However, they must be present during the count. An auditing firm may be hired, particularly when verifying employee honesty or seeking expert opinions. All commission members must sign the inventory lists and reports—missing even one signature invalidates the inventory.
Not all new entrepreneurs understand what inventory in a store entails or recognize its importance, leading to insufficient attention to this process. This can result in reduced profits or fines from regulatory agencies monitoring product storage conditions and expiration dates. Timely inventory prevents violations that negatively impact store operations.